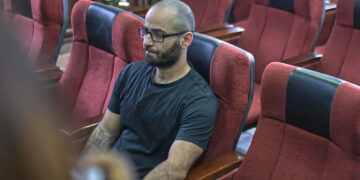
Tigran Gambaryan, the head of financial crime compliance at Binance, has been released from custody in Nigeria after spending nearly eight months under detention. Mr Gambaryan, an American citizen who was apprehended alongside another Binance executive earlier this year, had faced allegations of involvement in money laundering activities totalling $35 million, as well as claims that Binance operated without requisite licensure within Nigeria. His release was reportedly facilitated by diplomatic intervention, amid reports of deteriorating health while held in Kuje prison.
A Nigerian federal court ruled for Mr Gambaryan’s release after the Economic and Financial Crimes Commission (EFCC) formally dropped the charges, allowing him to leave Nigeria for medical care abroad. Legal experts suggest the EFCC’s withdrawal of charges followed behind-the-scenes diplomatic pressures from the United States, an assertion that aligns with recent reports from Financial Times sources, though officially unacknowledged by both Nigerian and U.S. authorities.
The saga began when Mr Gambaryan and a senior colleague from Binance’s Africa division visited Nigeria in February at the government’s invitation. Shortly after their arrival, the two were detained under accusations of money laundering and operating a financial platform without a local licence. While the EFCC’s allegations involved substantial sums linked to illicit financial flows, both Binance and Mr Gambaryan have consistently repudiated the accusations as baseless.




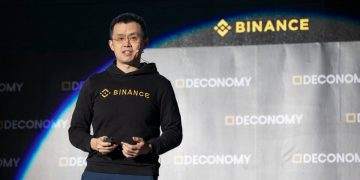
Despite this recent acquittal, Binance as a corporate entity remains under scrutiny. The company, which has had an increasingly strained relationship with global regulators, will face separate proceedings in Nigeria come November. This follows a series of escalating legal and regulatory confrontations involving Binance worldwide, notably a high-profile case in the United States earlier this year. In April, Binance’s founder entered a guilty plea in a U.S. court over separate allegations, with the U.S. Treasury criticising the company for allegedly permitting transactions that may have facilitated the activities of proscribed entities.
The outcome of the November hearing may further define Binance’s operational landscape across Africa, where it remains a significant player in cryptocurrency. The broader implications for international crypto regulation also remain to be seen, as governments wrestle with the enforcement of financial compliance on decentralised platforms.
In light of Mr Gambaryan’s release, his legal team underscored that their client will seek a thorough investigation into his detention. While Binance declined to comment, a company representative reaffirmed Binance’s commitment to legal compliance and cooperation with regulatory bodies.
As this unfolding narrative suggests, cryptocurrency companies navigating international operations face increasingly sophisticated compliance expectations, as governments endeavour to curtail the risks posed by digital finance to global security and financial stability.